


As Singapore authorities worked to test the foreign workers’ dormitories, Singapore’s construction sector grinded to an almost complete halt. The Ministry of Trade and Industry (MTI) stated that Singapore’s construction sector contracted by 54.7% on a year-on-year basis in 2Q20.
Amongst those companies affected is Koh Brothers Group Limited – a construction, property development and specialist engineering solutions provider. In this article, we examine the company’s bond, the KOHSP 5.100% 27Oct2022 Corp (SGD).
As the company draws most of its revenue from construction projects, its 1H20 results have been adversely affected, with revenue declining by 35% year-on-year, and the group making a net loss of S$17.8 million. Despite its poor performance in the first half of the year, its balance sheet remains resilient in our view due to its contract assets and development properties. In fact, the company was cash-flow positive mainly due to billing of contract assets to customers.
On Koh Brothers’ balance sheet lies S$97.3 million of contract assets that will be recognised as revenue up to 2027. The group’s subsidiary, KBD Ventures, is developing Van Holland, a freehold condo estimated to be worth S$132 million on its balance sheet. If we estimate the potential cash inflow from contract assets and sales of Van Holland, the Group appears to have sufficient assets to pay off its liabilities in the future.
Table 1
Company’s shortened balance sheet
|
S$ '000 |
|
|
Significant current assets |
|
|
Trade and other receivables |
58,067 |
|
Investment securities |
3,537 |
|
Cash |
91,481 |
|
Contract assets |
97,364 |
|
Development properties |
132,396 |
|
Investment in associated companies |
1,276 |
|
Amounts due from joint ventures |
56,912 |
|
441,033 |
|
|
Significant noncurrent assets |
|
|
Investments in joint ventures |
96,912 |
|
Investment properties |
94,414 |
|
PPE |
141,445 |
|
332,771 |
|
|
Total significant assets |
773,804 |
|
Significant current liabilities |
|
|
Trade and other payables |
70,529 |
|
Contract liabilities |
19,651 |
|
Amounts due to JV |
18,684 |
|
Bank borrowings and lease liabilities |
94,504 |
|
203,368 |
|
|
|
|
|
Significant non-current liabilities |
|
|
Trade and other payables |
6,742 |
|
Bank borrowings and lease liabilities |
207,947 |
|
Notes payables |
70,000 |
|
284,689 |
|
|
Total significant liabilities |
488,057 |
|
Source: Company's financial statement
for 1H20 |
|
Table 2
Analysis of assets and liabilities
|
S$'000 |
|
|
Assets that could be liquidated/monetised |
|
|
Trade and other receivables |
58,067 |
|
Investment securities |
3,537 |
|
Cash |
91,481 |
|
Contract assets |
80,000 |
|
Development properties |
99,297 |
|
Investment in associated companies |
1,351 |
|
Amounts due from joint ventures |
56,912 |
|
Estimation of non-current assets |
262,049 |
|
652,694 |
|
|
Liabilities that could be paid off before bond's maturity |
|
|
Current Trade and other payables |
70,529 |
|
Contract liabilities |
19,651 |
|
Amounts due to JV |
18,684 |
|
Non-current trade and other payables |
6,742 |
|
Short-term bank loans |
92,152 |
|
Notable loans payable within bond maturity date |
111,002 |
|
Notes payables |
70,000 |
|
388,760 |
|
|
Source: Company's financial statement for 1H20, iFAST estimates |
|
Furthermore, most of Koh Brothers’ loans are secured – mortgaged using land and buildings among others. In our view, the group should be able to maintain its support from lending banks, given its manageable leverage (debt over assets of 45.6% as of end-June).
Table 3
Aggregate amount of Group's borrowings and debt securities
|
Secured S$ '000 |
Unsecured S$ '000 |
|
|
Amount repayable in one year or less, or on demand |
31,175 |
60,977 |
|
Amount repayable after one year |
193,807 |
76,364 |
|
Source: Company's financial statement for 1H20 |
||
We estimate a liquidation value of 50% for the Group’s PPE and the instalment amounts of bank loans that the group has to pay by the maturity of the S$70m KOHSP 5.1% ‘22s. Our calculation shows the group has a healthy surplus over its liabilities. On the other hand, if we exclude non-current assets, the group roughly has a safety margin of just about S$1.9 million. Taking into account Koh Brothers’ operating income, cash changes and free cash flow over the years, we think the group is likely able to redeem its bond in 2022.
Table 4
Operating income and cash flow
|
In S$ millions |
12M ending 30 Jun 20 |
2019
|
2018 |
|
Operating income |
-18.0 |
-0.6 |
0.6 |
|
Free cash flow |
9.8 |
-22.2 |
-160.0 |
|
Net changes in cash |
38.9 |
52.7 |
-29.1 |
|
Source: Bloomberg Finance L.P., iFAST compilations |
|||
As construction activities were affected by COVID-19 and circuit breaker measures, Koh Brothers made a net loss of S$17.75 million in 1H20, although cash increased S$6.3 million over the same period. With local COVID-19 cases in Singapore dwindling to single-digit numbers and sometimes zero, construction activity should be picking up. As such, the group has likely gone through the worst of the current crisis in 1H20. And with sales of Van Holland and progress billing of contract assets, it should be unlikely that the group will fail to meet its debt obligations.
Relative valuation
We compare Koh Brothers with GSH Corp, Tuan Sing Holdings and Chip Eng Seng. If we look at leverage, Koh Brothers and GSH are at similar levels and are the healthier companies in the group. Negative EBIT over interest might be concerning for Koh Brothers but as we mentioned above, the group should be able to build up a healthy cash position by the bond’s maturity date.
Table 5
Peer comparison
|
1H20 key ratios |
EBIT over interest (x) |
Net debt over equity (%) |
Net debt over capital (%) |
|
GSH Corp Ltd |
0.83 |
72.36 |
41.98 |
|
Koh Brothers Group Ltd |
-3.46 |
92.81 |
48.13 |
|
Tuan Sing Holdings Ltd |
0.45 |
137.45 |
57.89 |
|
Chip Eng Seng Corp Ltd |
-1.02 |
155.51 |
66.30 |
|
Source: Bloomberg Finance L.P., iFAST estimates |
|||
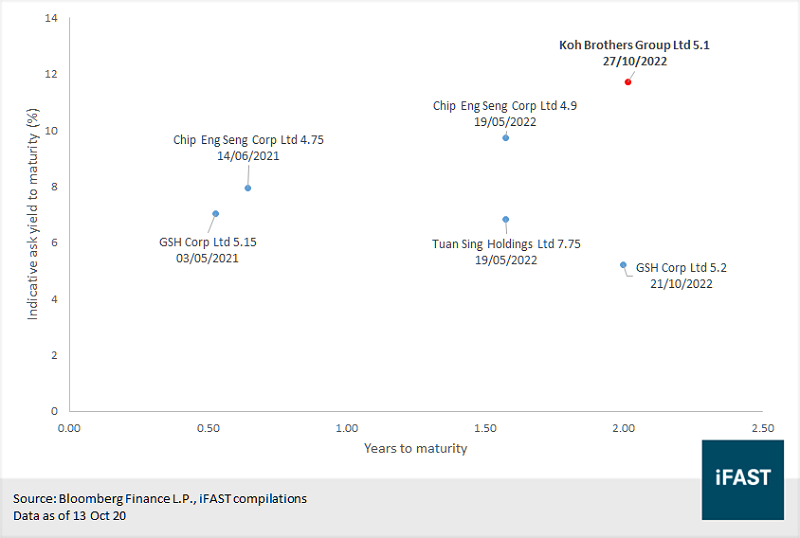
Looking at yields, the KOHSP 5.100% 27Oct2022 Corp (SGD) is the cheapest among them and we think it is good value if one can acquire the bonds at an ask yield of about 10%. The bond has a firm ask price of 96 (ask yield of 7.25%) and bid price of 86 (bid yield of 13.18%) as of Oct 14.
Figure 1
Koh Brothers bonds look the most attractive
As
Singapore draws closer to an announcement of Phase 3 reopening, Koh Brothers should
soon be able to turn its fortune around. Construction activity rebounded in
3Q20, growing by 38.7% QoQ seasonally adjusted, although declining by 44.7% on
a YoY basis. The rebound should be able to continue, and the group will benefit
from that. With projects in the work, we are positive on the KOHSP 5.100% 27Oct2022 Corp (SGD).
References:
Ministry of Trade and Industry, Singapore’s GDP Contracted by 12.6 Per Cent in the Second Quarter of 2020: https://www.mti.gov.sg/-/media/MTI/Newsroom/Press-Releases/2020/07/AdvEst_2Q20.pdf
Ministry of Trade and Industry, Singapore’s GDP Contracted by 7.0 Per Cent in the Third Quarter of 2020: https://www.mti.gov.sg/-/media/MTI/Newsroom/Press-Releases/2020/10/AdvEst_3Q20.pdf
Declaration: For specific disclosure, at the time of publication of this report, IFPL (via its connected and associated entities) and the analyst who produced this report hold a NIL position in the abovementioned securities.
Our podcast series, Yield Hunters, is available on Spotify and iTunes Podcasts and Google Podcasts. We share our thoughts on new bond issues and hold discussions on the fixed income space. Listen to our latest episode below and follow us!










